Recovery
Houston Insurance Claims Help
Photographs and a clear record of the damage, for you and your adjuster.
Serving Houston since 1993
The work
About Insurance Claims Help
When a roof or a pipe lets water in, a clear record helps the conversation with your insurer. We photograph the damage, note where the water went, and put that documentation with the repair scope.
We do not decide what your policy covers. Your insurer does. If you want a room-by-room record of your own before anything is moved, the insurance photo log on this site is free to use.
What is included
- Inspection photos of roof, water and storm damage
- Notes on what was wet and what was repaired
- Documentation you can share with your adjuster
- A free room-by-room photo log you can fill out yourself
- Drying and repairs once the house is protected
Built for Houston
A record of what the storm or the leak did.
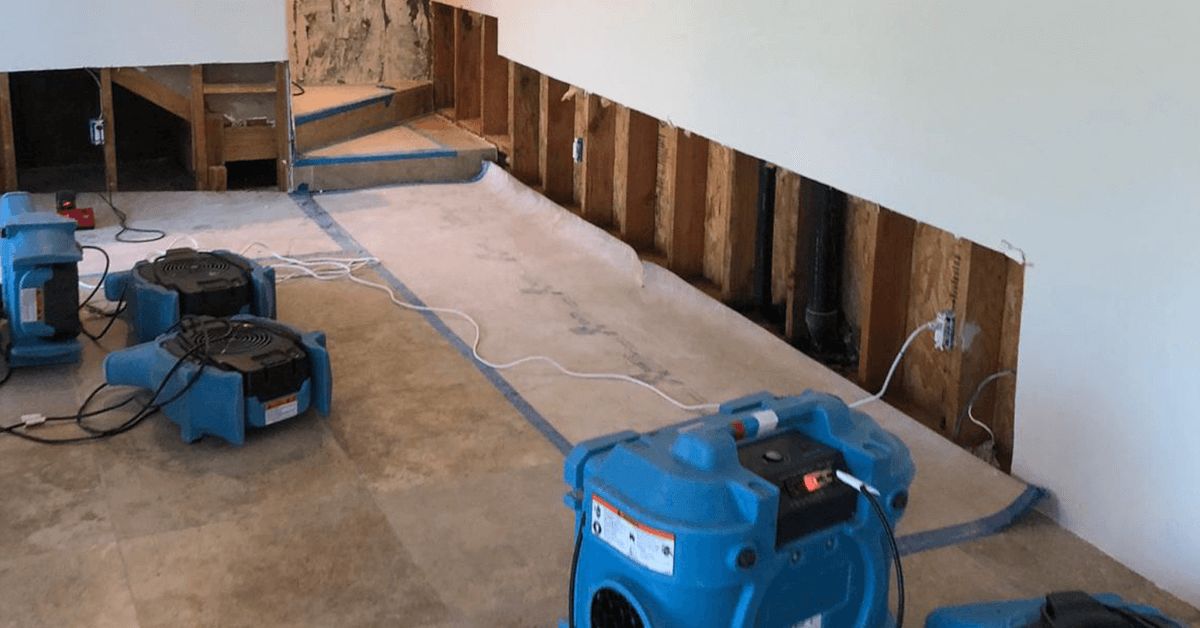
Houston claims we document usually start with a roof opening, a supply line, an appliance, or water that came in at grade. We photograph the conditions and the scope of drying and repair.
The photo log is yours to use whether or not you hire us for the work. It is a room-by-room packet, not a promise about what the policy will pay.
01
Photos before cleanup
Wide shots and close shots of the opening, the wet rooms, and the belongings, taken before they are moved.
02
What we write down
Where the water went, what was dried, and what was repaired. Your insurer uses that record however the policy allows.
03
The building, separately
Stopping more water and drying the structure do not wait on a coverage decision. We say which work is protection and which work is the rebuild.
In and around
Houston · Westchase · Alief · Katy · Sugar Land · Bellaire · Memorial · Spring Branch
How it goes
What to expect, step by step.
- 01
Make the scene safe
Stop more water if you can do that safely. Stay out of wet rooms with damaged ceilings or live power. Call (713) 909-0034 if water is still coming in.
- 02
Photograph before you toss
Wide shots, close shots, the source, and the belongings, before they are bagged. The photo log on this site is a room-by-room way to do that yourself.
- 03
Notice the insurer
Call the company on the policy or the agent who can open a claim. Ask how they want notice. Write down the claim number. We do not quote you a deadline. The policy does.
- 04
We document the building
Our photos and notes cover what was wet, what was dried, and what was repaired. You can share them. They are not a coverage opinion.
- 05
Dry and protect
Tarping a safe roof and drying wet structure do not wait on a meeting. Many policies expect you to limit further damage. That work is still not a promise of reimbursement.
- 06
Rebuild as construction
The repair is a scope and a price. The claim payment is whatever the insurer allows. We keep those labeled separately, and we do not negotiate the claim.
What this is
Photos and a clear record. Not a coverage decision.
Insurance claims help, here, means inspection photos and notes on water or storm damage, tied to the work if you hire us to dry or rebuild. It does not mean we file the claim for you, interpret the policy, or argue with the adjuster. Your insurer decides what is covered. We are not a public adjuster. The free insurance photo log is yours whether or not you hire us. It is a packet, not a promise about payment.
The losses we document most often start with a roof opening, a supply line, an appliance, or water that came in at grade. Those are different facts. A homeowners policy often treats them differently, and flood from rising water is often a different policy entirely. We describe what we can see. We do not rename a flood as a sudden plumbing break because the second phrase sounds more payable.
01
Your photos first
If it is safe, shoot the rooms before you clean. Thrown-away belongings and a mopped floor are hard to explain later. Do not wait on us to take the only pictures.
02
Our photos second
We add the conditions we find, the moisture, the tear-out, and the repair. They are specific. They are not a narrative written to chase a number.
03
Two different jobs
The paper and the construction stay separate. Drying a house is not “handling the claim.” Building it back is not a settlement.
Records
What to write down, and what we will write down.
Write the date you noticed the damage, who you called, and the claim number. Keep the failed hose or the fitting if you can do it safely. Note whether water came from a pipe, from the roof, or from the street. Ask the insurer what they want saved and whether they want to see anything before it is removed. Notice language is in the policy. It is not the same on every Texas policy, so we will not invent “you have 48 hours” or any other deadline.
When we are on the loss, the notes say where the water went, what was dried, what was removed, and what was rebuilt. Photos are taken before a tarp covers an opening when that is safe, and before new drywall closes a wall. You may give that set to the adjuster. We can walk an adjuster through what we saw of the building. We do not negotiate the dollar figure and we do not sign your claim over to ourselves.
01
The photo log
The log on this site is room by room. Use it the day of the loss if you want a structure. It is free. It does not create coverage.
02
Cause in plain words
“The supply line under the sink failed” is a fact if that is what happened. “The policy should pay” is not a fact we will write.
03
Depreciation
Some policies pay actual cash value first and hold recoverable depreciation until the work is done. Some do not. The wording is yours. We do not calculate it for you.
Cost
The construction price and the claim are different.
We do not publish a separate price list for documentation. Photos and notes ride with the inspection, the drying, or the repair you hire. The construction price is the scope of that work. For scale, a contained one-room water loss often plans around $1,500 to $5,000, a room that needs drywall and flooring often around $5,000 to $15,000, and a larger loss often around $15,000 to $50,000 or more. An asphalt roof replacement on many Houston houses plans around $12,000 to $24,000. Those are planning ranges for the building, not a prediction of the check.
The insurer’s figure and our estimate measure different things, and they can differ. A percentage wind or hail deductible, often one, two, or five percent of the dwelling limit on Texas policies near the coast, can be larger than a plumbing deductible on the same policy. If the check is short of the scope, the conversation is about the scope. The estimate stays the work required to repair the house.
01
The claim stays yours
Hiring the drying or the repair does not assign the claim to us. You remain the person on the policy. We document the building.
02
Mitigation is still work
A tarp and a dry-out have a cost even when you hope the policy reimburses them. We price that work as work. Starting it is not an approval from the carrier.
03
Get the number from the visit
Call (713) 909-0034 or request an estimate. The address is 511 Crestwater Ct, Houston, TX 77082. The visit is how the scope, and then the price, gets decided.
Houston
Wind, plumbing, and flood are not the same story.
A spring hail storm, a hurricane-season opening in the roof, a burst hose in August, and water that came in from a bayou or a flooded street produce different documentation because they are different events. Hurricane season is June 1 through November 30. Hail is often earlier. Plumbing failures do not read the calendar. Rising water is the one people most often confuse with a homeowners claim. If the water came from outside and rose into the house, say that. Do not let anyone, including us, soften it into a phrase that sounds easier to cover.
Houses on slabs hide water under floors. Pier-and-beam houses drop it into the crawl space. The photos should show the path, not only the room that looks the worst. Older Heights and West University houses may have plaster. Newer Katy houses may have wet insulation in a big open ceiling. We document the assembly that is there. The permit for the rebuild, if plumbing, electrical, structure, or a full roof is involved, follows the address: City of Houston, an independent city, or the county. The claim does not replace the permit.
01
Limit further damage
Many policies expect you to protect the property. Cover an open roof when it is safe. Start drying. Keep the receipts and the photos. That is mitigation, not an admission you know the coverage.
02
Do not discard the source
The failed part helps the story. Bag it if you can. A repaired pipe with no photo of the break is a thinner record.
03
One company, labeled work
Tarping, drying, and the rebuild can stay with Elite Restorations, family-owned in Houston since 1993. The claim file and the construction file are still two files.
Questions
Good to know.
Do you file the claim or decide what is covered?
No. We provide inspection photos and documentation. Coverage decisions belong to your insurer.
Should I clean up before the photos?
Protect the house from more water, and photograph the damage before you throw things away. The insurance photo log walks a room at a time if you want to start that record yourself.
Can you dry and rebuild after the loss?
Yes. Tarping, drying, and the repairs to drywall, flooring and the roof can stay with the same team. The claim paperwork and the construction are separate jobs, and we keep them that way.
How do I reach you?
Call (713) 909-0034. If water is still coming in, say so. The emergency form on this site reaches the same team.
Do you file claims or negotiate with the insurer?
No. We photograph and note the damage and the work. Coverage, payment, and depreciation belong to your insurer. We are not a public adjuster.
Is there a fee for the documentation?
We do not publish a standalone price for documentation. Photos and notes are part of the inspection, drying, or repair you hire. The photo log on the site is free to use on your own.
What should I do before anyone arrives?
If it is safe, stop more water, photograph the rooms, and keep the failed part. Then call your insurer and call (713) 909-0034 if you want us on the building. Do not gut a room before it is documented.
Why might the insurance check and your estimate differ?
They measure different things. The check is what the policy pays. The estimate is the cost of the scope. Wind and hail deductibles on many Texas policies are a percentage of the dwelling limit and are not the plumbing deductible. We do not rewrite the work to force those numbers to match.
Often paired with
Google reviews
In their words.
4.8 stars from 87 Google reviews, read November 13, 2026. See the Google profile
Google review
Outstanding service from start to finish! When our water heater gave out and flooded our home, we were completely overwhelmed... They handled our entire insurance claim from start to finish, communicating directly with the adjuster and taking a massive weight off our shoulders. Their mitigation crew worked quickly and thoroughly to dry out the house... When it came time for the reconstruction, the craftsmanship blew us away. They didn't just restore our home; they rebuilt everything better than it was before the leak... They turned a stressful disaster into a seamless, positive experience, and we couldn't be happier with the results!
Christopher B.
Water heater flood
Google review
Elite Restorations truly came to my rescue during an emergency when all the water pipes burst at my Bryan property... They've completed renovations on multiple properties for me in Galena Park, Bryan, and Marlin, Texas, and every single time the results have been phenomenal... If you're looking for a reliable, skilled, and trustworthy team, Elite Restorations is it.
Catricia R.
Burst pipes
Greater Houston
Areas we serve
Insurance Claims Help is scheduled from our Houston office at 511 Crestwater Ct, 77082. The closest neighborhoods have their own pages. Every community below has a page for this service.
- Houston
- Westchase
- Alief
- Energy Corridor
- Katy
- Sugar Land
- Bellaire
- Memorial
- Spring Branch
- The Heights
- River Oaks
- West University
- Galleria Area
- Upper Kirby
- Rice Village
- Medical Center
- Bunker Hill
- Piney Point
- Hunters Creek
- Bear Creek
- Cinco Ranch
- Stafford
- Richmond
- Pearland
- Clear Lake
- Baytown
- Galveston
- Texas City
- The Woodlands
- Magnolia
Planning insurance claims help?
Serving Houston since 1993. Call (713) 909-0034 for a free estimate.